Singapore's Keppel DC REITAnd the parent company KeppelThese two data centers in the Tokyo metropolitan area of Japan 90% effective ownership interestWe've decided to acquire [company name]. With demand for data centers rising due to the expansion of AI services, this is a major deal aimed at securing long-term rental income in the Japanese market.
The two assets' The acquisition price, based on a 100% stake, is 190 billion yenBased on the exchange rate at the time of the announcement, this amounts to approximately $1.19 billion or S$1.5485 billion. Once the transaction is completed, Japan’s share of the rental income in the Keppel DC REIT portfolio will increase from about 9% to to 23% It's expected to rise.
However, the 190 billion yen figure is based on the total assets, and Keppel’s actual effective stake is 90 percent. It is important to distinguish between the transaction size and the ownership structure.
| By jointly holding a 90% effective stake
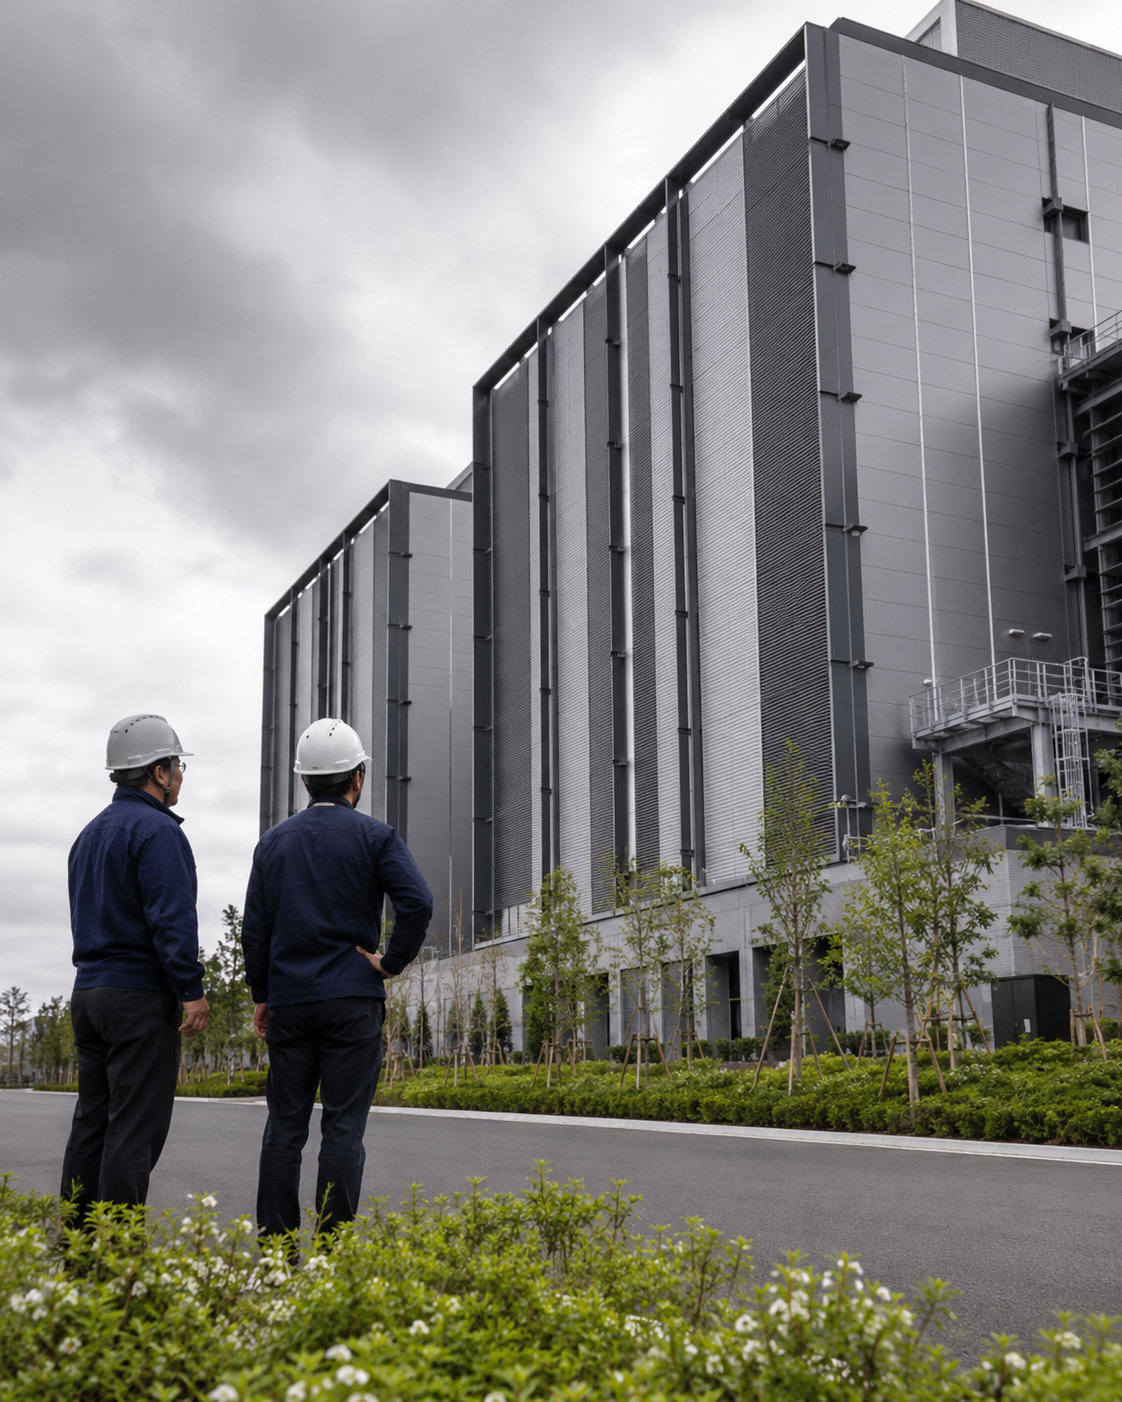
The target of the acquisition is located in Inzai City, Chiba Prefecture, Japan, Tokyo Data Centre 4Wow Tokyo Data Centre 5Hey. Keppel DC REIT's effective ownership interest in each facility 88.62%, Keppel holds a 1.38% stake, while the existing operator retains the remaining 10%.
Since the existing operator retains a partial stake, this allows for the alignment of investors’ and operators’ interests while maintaining continuity in facility operations. The amount Keppel DC REIT will pay for the 88.62% stake is approximately 168.4 billion yen...was presented as.
| 190 billion yen is the amount based on 100% of assets.
The 190 billion yen cited in the official announcement represents the purchase price based on a 100% valuation of both facilities. This amount was set at approximately 2.1% below the appraised value of 194 billion yen.
While news headlines may simply state that a 90% stake was purchased for 190 billion yen, the actual contract requires a breakdown of the total asset value and the payment amounts based on each investor’s effective stake. This distinction is crucial for accurately understanding the acquisition structure.
| Both facilities are fully leased.
Tokyo Data Center 4 and 5 are hyperscale colocation facilities based on freehold ownership, located in Inzai City, a hub for large data centers. Four investment-grade Internet and IT service companies are tenants there, and currently 100% LeasedIt's already done.
Colocation data centers generate rental revenue by providing power, cooling, networking, and server space to multiple customers. As demand for large-scale AI computing grows, the value of existing facilities with reliable power and connectivity may increase.
Given the potential for rent increases and the possibility of renewing the lease,
The average annual rent increase under the leases for the two facilities is approximately 2.8%. Keppel estimates that current rent is at least 30% below market rates and believes there is room to adjust the rent during the lease renewal process.
Based on leasable area, the weighted average remaining lease term is approximately 4.5 years for Center No. 4 and 10.6 years for Center No. 5. This combination offers one facility with relatively high potential for improved returns through lease renewals and another facility that provides revenue stability through long-term leases.
| The share of rental income from Japan rose from 9% to 23%
Upon completion of the transaction, Keppel DC REIT's total assets will amount to approximately 7.6 billion Singapore dollars...and the number of data centers it owns has grown to 27 across 10 countries. Japan’s share of the portfolio’s rental revenue has also increased from about 9% to 23%.
Singapore continues to account for the largest share, at about 60%, even after the transaction. While expanding into Japan helps alleviate the concentration risk in Singapore, it also means greater exposure to changes in Japanese interest rates, the yen exchange rate, and local power and regulatory conditions.
| By combining a rights offering with yen-denominated debt,
Keppel DC REIT will raise at least 600 million Singapore dollars We plan to carry out a private placement on a large scale and utilize our yen-denominated debt as well. Borrowing in local currency allows you to align the currency of rental income with that of your debt, thereby reducing some of the risk associated with exchange rate fluctuations.
However, issuing new shares could dilute existing investors’ stakes, and increasing debt could raise interest expenses. The company calculated that, assuming the transaction is completed in early 2025, it would result in an increase in the dividend per unit of approximately 2.6 percent, but, This figure does not guarantee actual future performance.
| We need to look at both AI data center demand and transaction execution
This acquisition demonstrates that demand for AI infrastructure is driving up the value not only of new facilities currently under construction but also of existing data centers where leases have already expired. Keppel’s strength lies in its ability to immediately add assets with prime locations, power supply, and long-term customers to its portfolio.
The transaction is Scheduled for completion in the fourth quarter of 2026So, it's not over yet. We need to verify the financing terms, actual interest expenses, the likelihood of customer contract renewals and power expansion, and whether rent increases in the Japanese market are proceeding as planned.
References
Tags
#Keppel #KeppelDCREIT #Tokyo Data Center #Injaishi #Data Center #AI Infrastructure #Hyperscale #Colocation #JapaneseRealEstate #REIT #DataCenterInvestment #Cloud Infrastructure